October 3, 2026
Institutions Reassess Defensive Building Blocks
Pension funds are increasing their focus on bullion as the traditional diversification provided by bonds shows signs of strain. For liability‑sensitive investors seeking a defensive anchor that is not tied to an issuer, gold offers a portfolio role that differs from duration‑based fixed income. The shift reflects a practical allocation choice rather than a cyclical trade: bullion’s value is not contingent on a borrower’s capacity to pay and it is less exposed to policy or credit events that can affect bond correlations during periods of inflation or interest‑rate volatility.
This recalibration comes with an important distinction inside the gold complex. For institutions wary of commodity‑price swings amplified by operational and financial leverage, direct bullion exposure provides access to the metal’s characteristics without the company‑specific risks embedded in mining equities. Those risks can include cost inflation, grade variability, permitting delays, geopolitical interruptions, and balance‑sheet or hedging outcomes that cause equity performance to diverge from movements in the underlying metal.
Why Bullion, Not Miners
Mining shares can offer torque to the gold price, but that same sensitivity raises dispersion across issuers and cycles. Production interruptions or capital‑intensive growth plans can dominate returns even in supportive metal markets. By contrast, bullion tracks the spot metal more directly. It carries no operating agenda, does not issue guidance, and is not exposed to equity market dynamics such as index flows or corporate actions. For allocators charged with matching long‑dated liabilities, that clarity of exposure is the appeal.
Liquidity and custody frameworks have also matured. Institutions can implement bullion exposure within established governance, risk, and reporting processes, and can ring‑fence holdings from broader market plumbing. The result is a cleaner hedge profile alongside other defensive assets when cross‑asset correlations become unstable.
Implementation Considerations
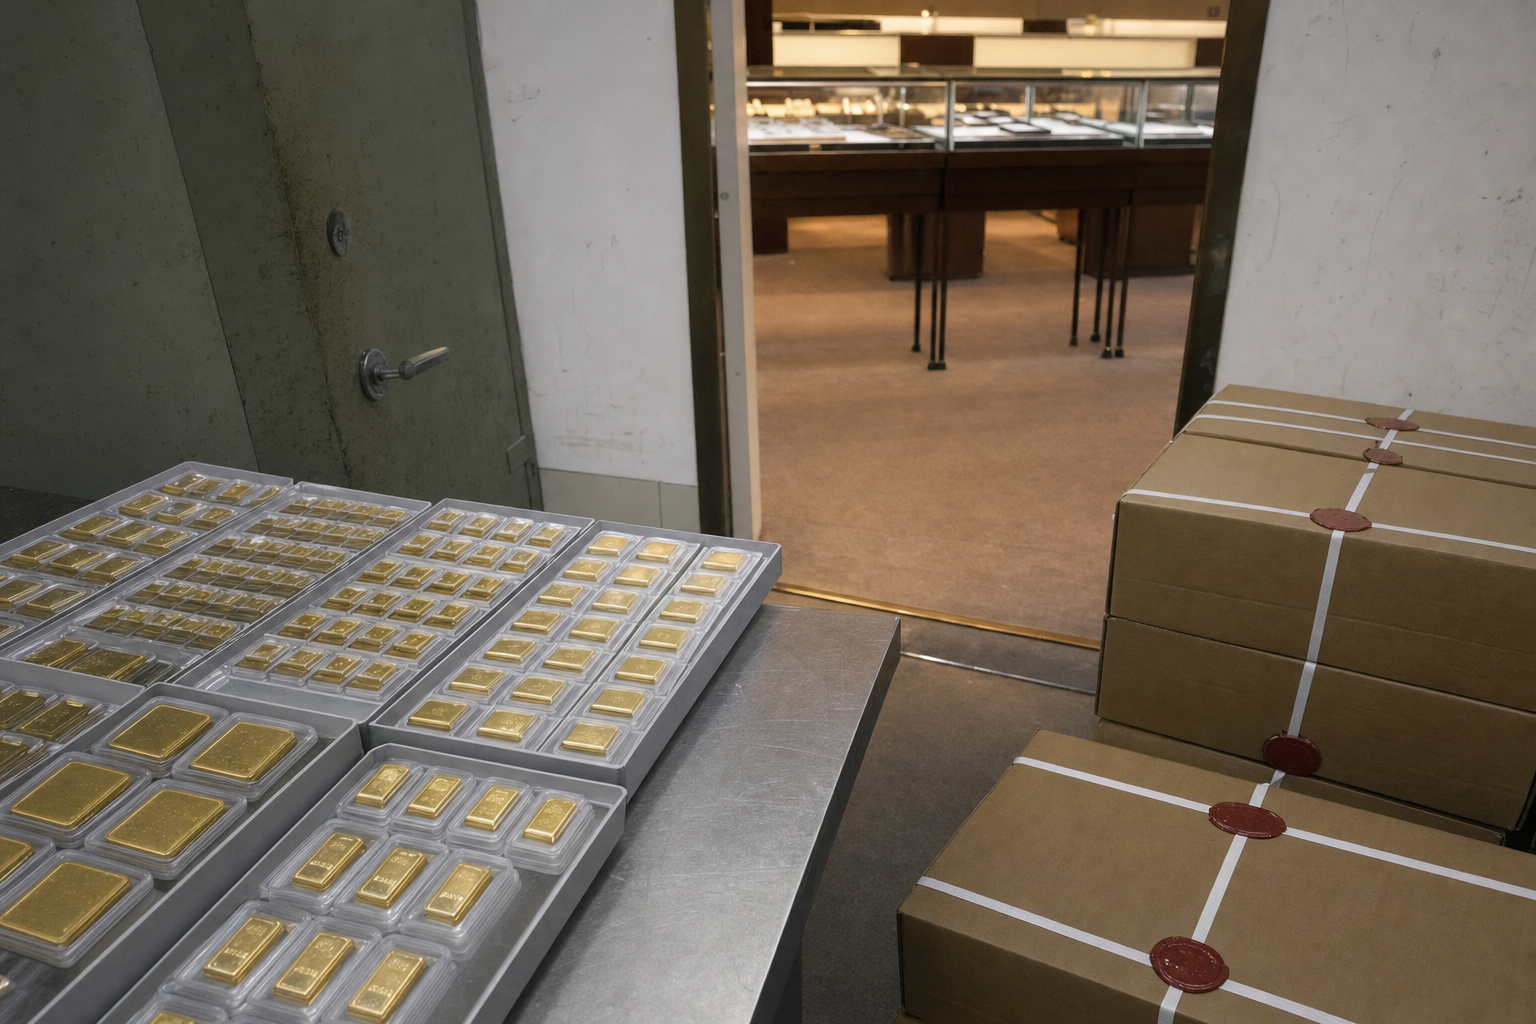
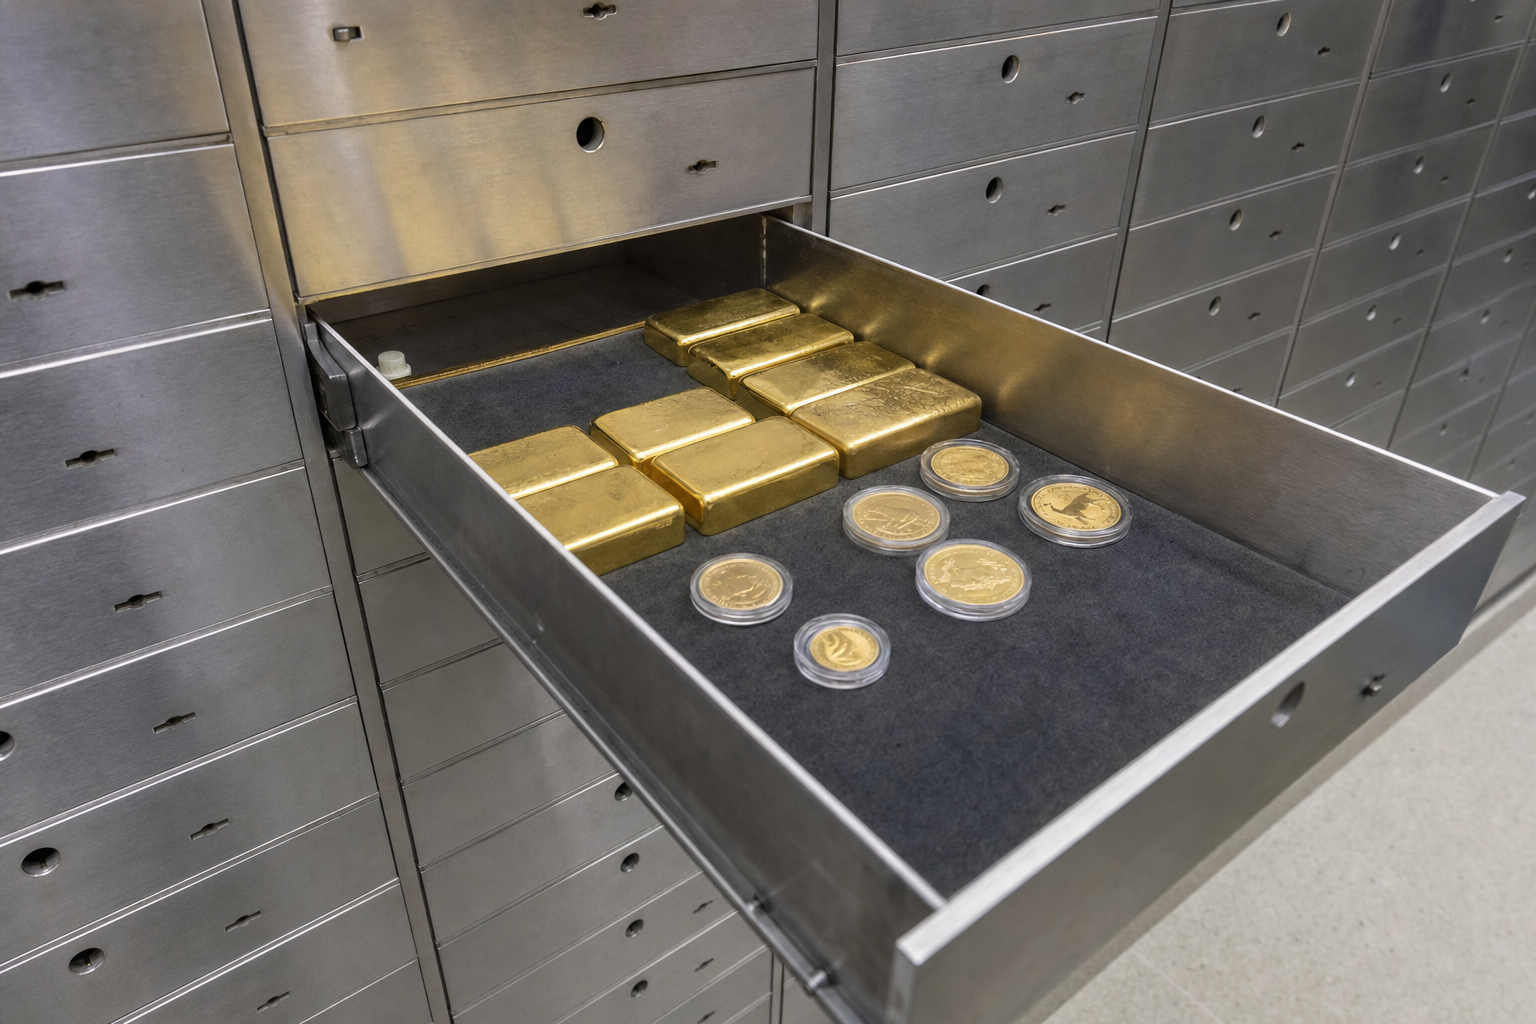
Portfolio design typically weighs tracking precision to the metal price against operational, custody, and counterparty risks. Where the objective is to minimise issuer and intermediary exposure, fully allocated holdings segregated in recognised vaults can align with policy constraints on collateral quality and rehypothecation. Rebalancing mechanics, audit trails, and settlement timelines remain key operational points for investment committees.
None of this replaces fixed income’s role in income generation or liability matching. Rather, it acknowledges that in regimes when bonds’ diversification benefits weaken, bullion can serve as a complementary ballast with a different risk transmission path. In this context, fully allocated, vaulted bullion offers direct exposure without issuer credit risk.