October 15, 2026
Kazakhstan Shifts Reserve Mix Toward Dollars
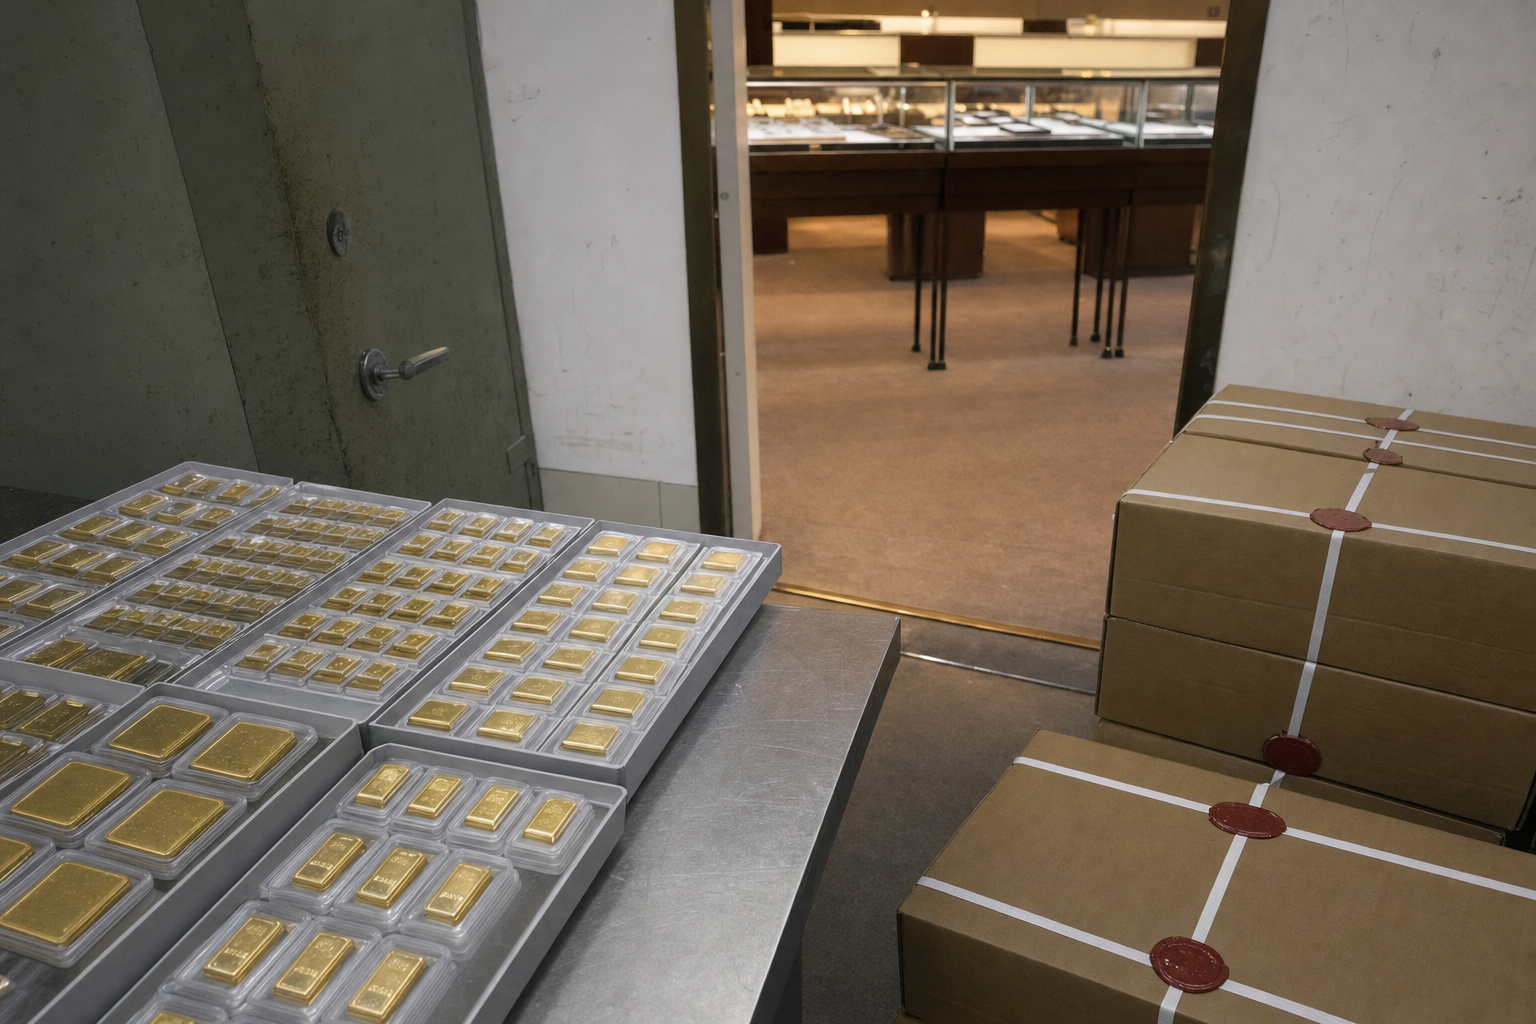
Kazakhstan’s central bank plans to reduce its concentration in gold after the metal rose to 78% of the country’s international reserves. The National Bank of Kazakhstan indicated it will sell part of its bullion holdings to rebalance the portfolio, marking a notable pivot from being one of the world’s more active official-sector buyers to a net seller for the remainder of 2026.
Deputy Governor Aliya Moldabekova framed the move as a response to market conditions and portfolio risk. With gold dominating the reserve mix, the bank aims to diversify holdings and increase exposure to dollar assets. The stated horizon for sales runs through year-end 2026, with the pace and size geared to achieving a more balanced composition rather than targeting price outcomes.
Yield Dynamics Undercut Gold’s Relative Appeal
Multi‑decade highs in U.S. Treasury yields were cited as a key driver. “We haven’t seen levels like this in a long time,” Moldabekova said. “This makes the dollar an attractive option, thereby reducing the appeal of gold as an investment asset.” Elevated nominal and real yields increase the opportunity cost of holding non‑yielding assets such as bullion, strengthening the case for reallocating a portion of reserves into interest‑bearing securities.
The bank’s characterization of its current reserve mix underscores the shift: a heavy single‑asset concentration is being recalibrated toward a broader blend of instruments. While no specific sale volumes or instruments were detailed, the policy direction suggests steady official‑sector supply from Kazakhstan into the bullion market alongside incremental demand for high‑grade dollar assets.
Market Considerations
Official‑sector flows are only one component of the gold market, but a turn from a consistent buyer to a seller can influence physical availability and investor sentiment at the margin. The impact will depend on the cadence of Kazakhstan’s transactions, broader central‑bank activity, and the evolution of global rates and the dollar. With the policy framed as reserve management rather than a market call, execution is likely to be phased and sensitive to liquidity conditions.
For investors tracking the interaction between gold and rates, the message is straightforward: higher carry in sovereign bonds increases competition for capital within reserve portfolios, while strategic motives—liquidity, safety, and diversification—continue to anchor gold’s role over longer horizons.
Allocated, vaulted precious‑metal holdings owned by private investors are distinct from central‑bank reserves and are not subject to policy‑driven liquidation schedules.