October 3, 2026
Gold–Bond Divergence Comes Into Focus
A long-observed linkage between gold and bond yields has loosened, prompting a reassessment of risk across the precious metals complex. The divergence raises a central question for mining investors: if bullion is being driven by forces other than yield dynamics, how should capital be positioned across producers, developers and explorers?
In conversations around the Beaver Creek circuit, the discussion has turned to market breadth. Senior producers have typically been first responders to shifts in bullion sentiment, but when bullion strength is not moving in step with rates, the equity market’s risk ladder can re-order. That places attention on whether capital will extend beyond the largest balance sheets to earlier‑stage projects.
Juniors: Funding, Optionality and Execution Risk
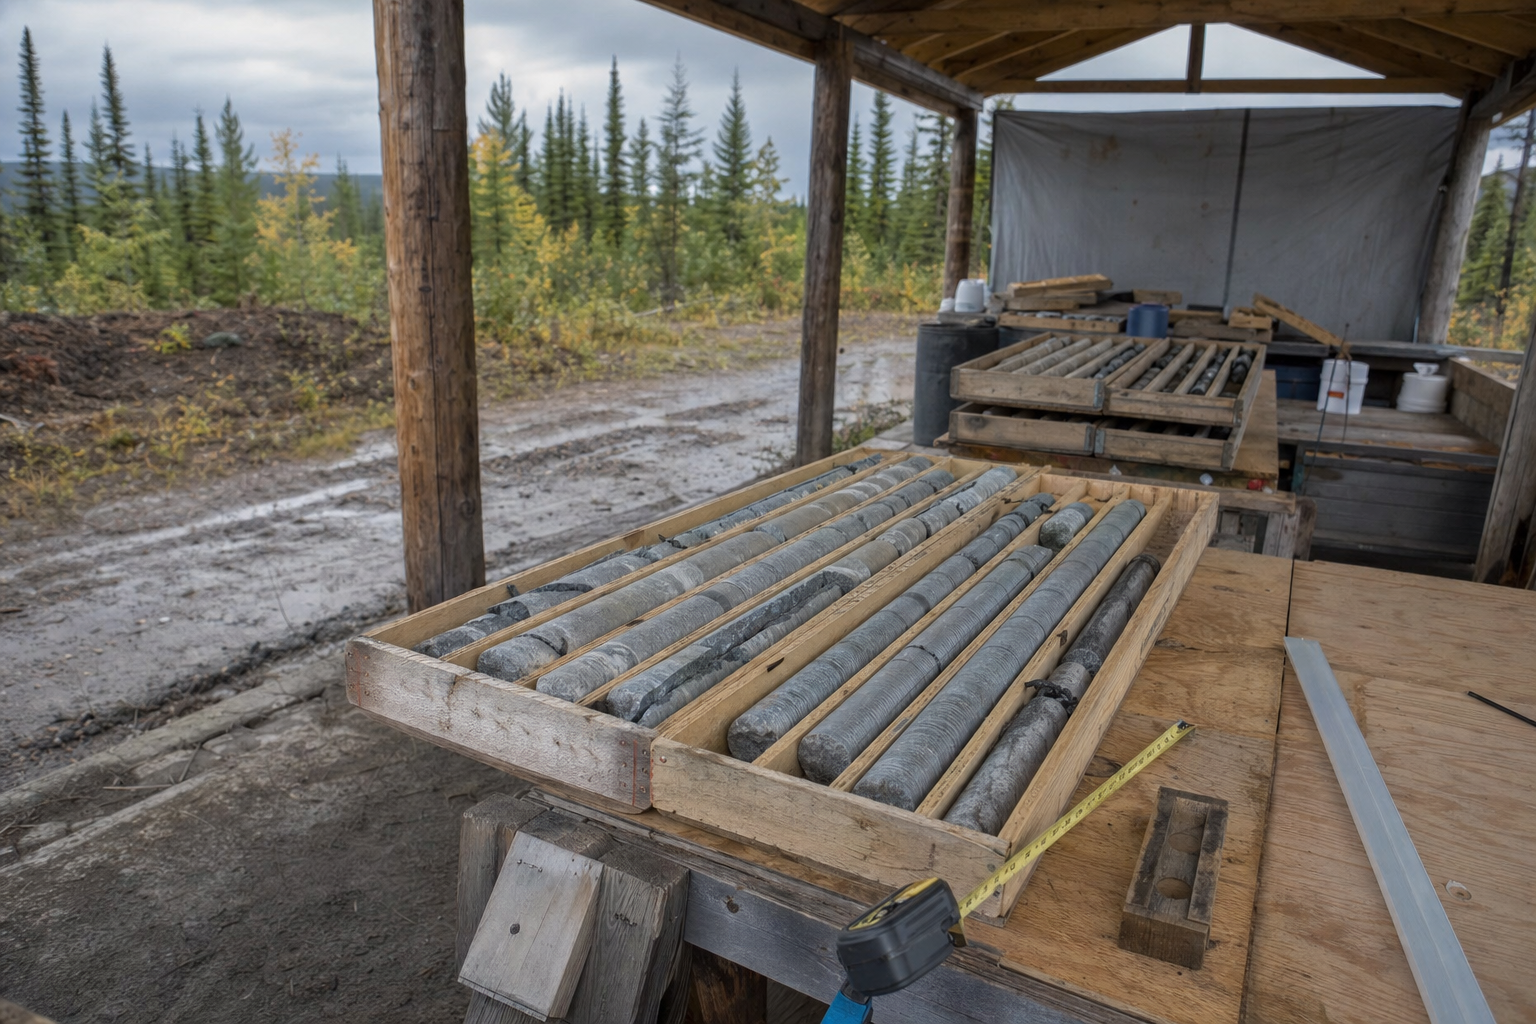
For junior miners, the path to value creation runs through drilling results, resource definition, permitting and project de‑risking. These companies are disproportionately reliant on external capital — public equity issuance, strategic investments, royalties and streams — and their ability to access funding often hinges on broader sector risk appetite. A period in which bullion asserts itself independently of bond moves can, historically, coincide with renewed interest in pipeline growth, optionality and discoveries.
That does not dissolve execution risk. Exploration outcomes remain uncertain, timelines can be lengthy, and permitting frameworks are jurisdiction‑specific. Cost inflation, access to skilled labour, and supply‑chain reliability continue to set the cadence of work programs. Where advanced projects carry established resources and engineering studies, corporate activity can become a parallel route to realization, with acquirers seeking reserve replacement or district consolidation. Any re‑rating in one subset of names can reset comparables across peers, but dispersion typically stays high, reinforcing the importance of asset quality and balance‑sheet resilience.
What Market Participants Are Watching
- Breadth within mining equities: whether flows extend from senior producers into developers and explorers, or remain concentrated in a handful of liquid names.
- Primary issuance conditions: the reopening of equity windows for juniors, including the pricing and size of raises relative to recent trading ranges.
- Project milestones: the cadence of drill programs, resource updates, economic studies and permitting decisions that can translate bullion sentiment into security‑specific catalysts.
- Corporate actions: indications that producers and intermediaries are prepared to deploy capital into advanced projects through acquisitions, joint ventures, royalties or streaming structures.
- Macro context: the durability of gold’s divergence from bond yields, and whether other cross‑asset signals reinforce or challenge the move.
The current episode underscores the distinction between owning bullion outright and owning mining equities, which add exploration, permitting and financing risk on top of commodity exposure.