October 5, 2026
Shift in Balance Highlighted
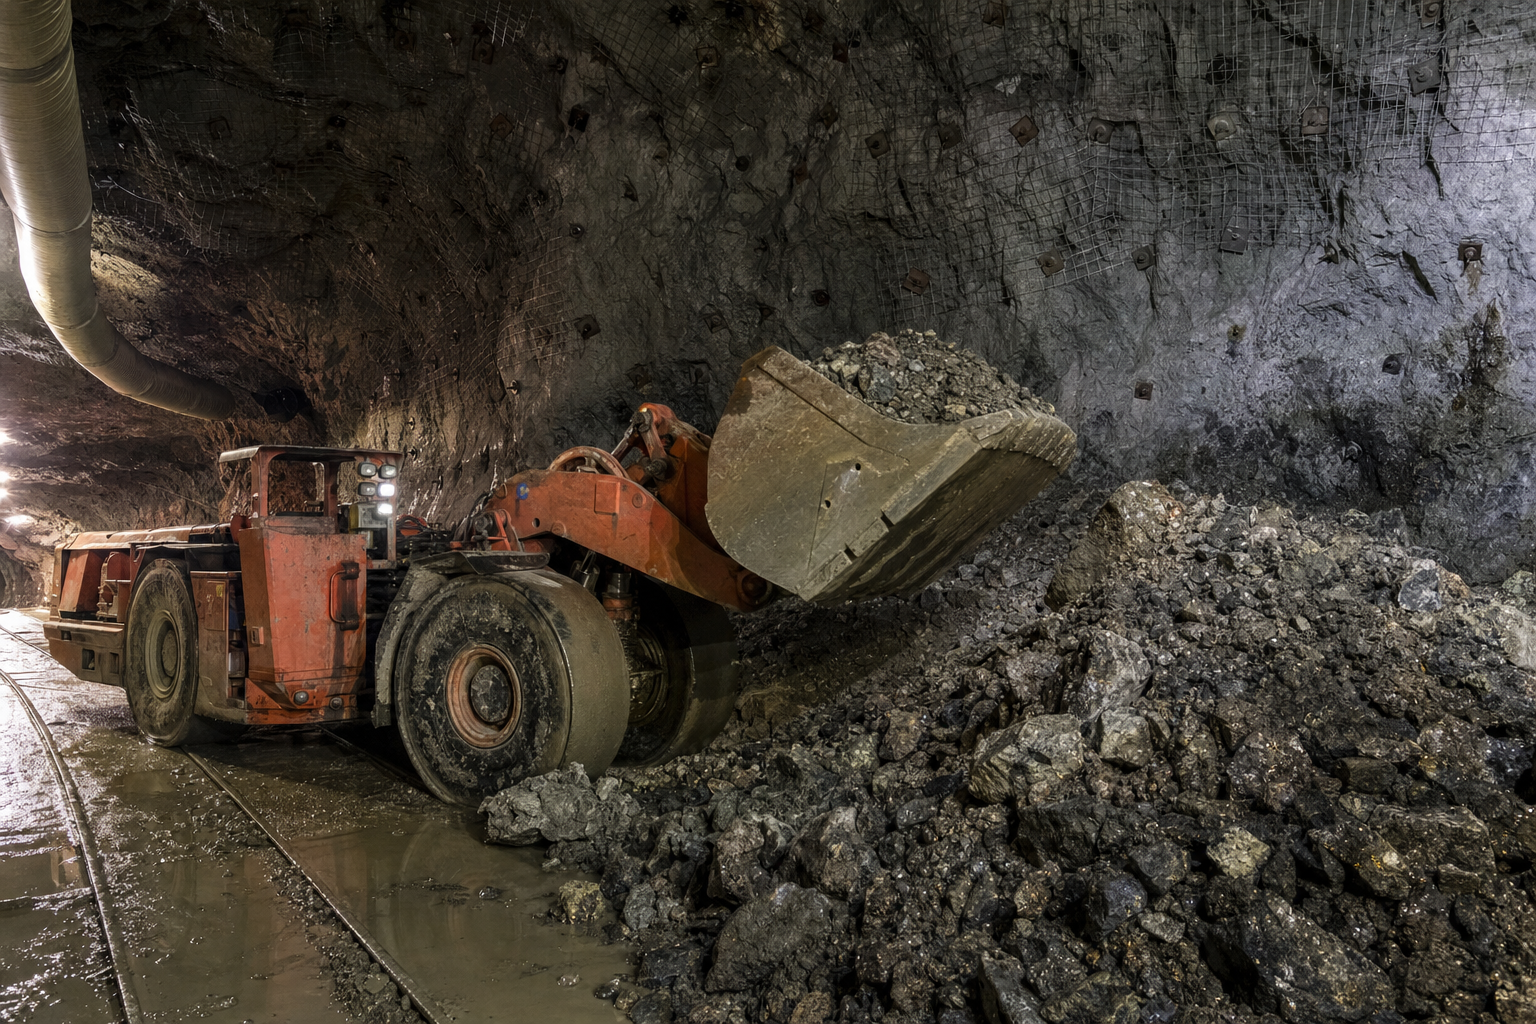
Silver’s multi‑year shortage could give way to a surplus as early as 2027, in an assessment that reframes how the market is thinking about the metal’s next phase. The prospective turn suggests silver may struggle to keep pace with gold even if the broader precious metals complex benefits from supportive macro conditions.
The change in tone centers on scarcity. After a period characterised by constrained availability, particularly as industrial demand intersected with uneven supply growth, the suggestion of a future surplus implies that incremental supply could meet or exceed expected offtake later in the decade. Without relying on specific projections, the direction of travel is what matters for positioning and relative performance discussions.
Relative Performance Lens
A prospective surplus carries clear implications for how silver trades against gold. Silver’s dual identity—part monetary asset, part industrial input—often amplifies its sensitivity to fabrication cycles across electronics, photovoltaics and other applications. If scarcity eases, that cyclical exposure can become more prominent, tempering silver’s ability to outperform gold during periods when safe‑haven and monetary dynamics dominate the precious metals narrative.
Gold, by contrast, is more tightly anchored to macro variables such as real yields, currency dynamics and official‑sector behaviour, with comparatively limited industrial pull. In an environment where both metals can be supported by broader financial conditions, any softening of the scarcity premium in silver may narrow the set of scenarios in which it leads on a sustained basis.
What the Market Will Watch
Attention now turns to the supply and demand levers that could validate or challenge a surplus thesis. On the supply side, market participants will monitor mine ramp‑ups, by‑product output from base‑metal operations and the responsiveness of secondary flows. On the demand side, trends in photovoltaics, electronics, brazing alloys and traditional fabrication channels will be scrutinised for evidence of substitution, thrifting or efficiency gains that could moderate silver intensity.
Inventory signals—whether in visible warehouses or along the semi‑fabricated supply chain—will also help clarify whether tightness is easing or simply rotating between regions and uses. The interplay between fabrication seasonality and investment flows remains a further variable in how quickly a perceived surplus would transmit into pricing and term‑structure behaviour.
The prospect of a transition from shortage to surplus does not preclude strength across the precious metals complex; it frames how that strength might be distributed between gold and silver. For holders of allocated physical metal, these shifts underscore the importance of understanding the different demand profiles that drive each metal’s cycle.