October 7, 2026
Official Sector Maintains August Buying Pace
Central banks continued to expand gold reserves in August, with net purchases totaling 39 tonnes for the month. Industry data indicate that the steady accumulation seen through the year persisted into late summer, extending the official sector’s role as a consistent source of physical demand. Large, repeat buyers remained active, with China, Uzbekistan and Poland leading reported additions.
The 39‑tonne net figure reflects the combined effect of gross purchases and sales reported by reserve managers, as well as routine adjustments and reclassifications. While individual monthly flows can vary with domestic objectives and foreign‑exchange conditions, the August total underscores continued preference among several central banks to add bullion to their strategic assets.
Repatriations And Vault Rebalancing
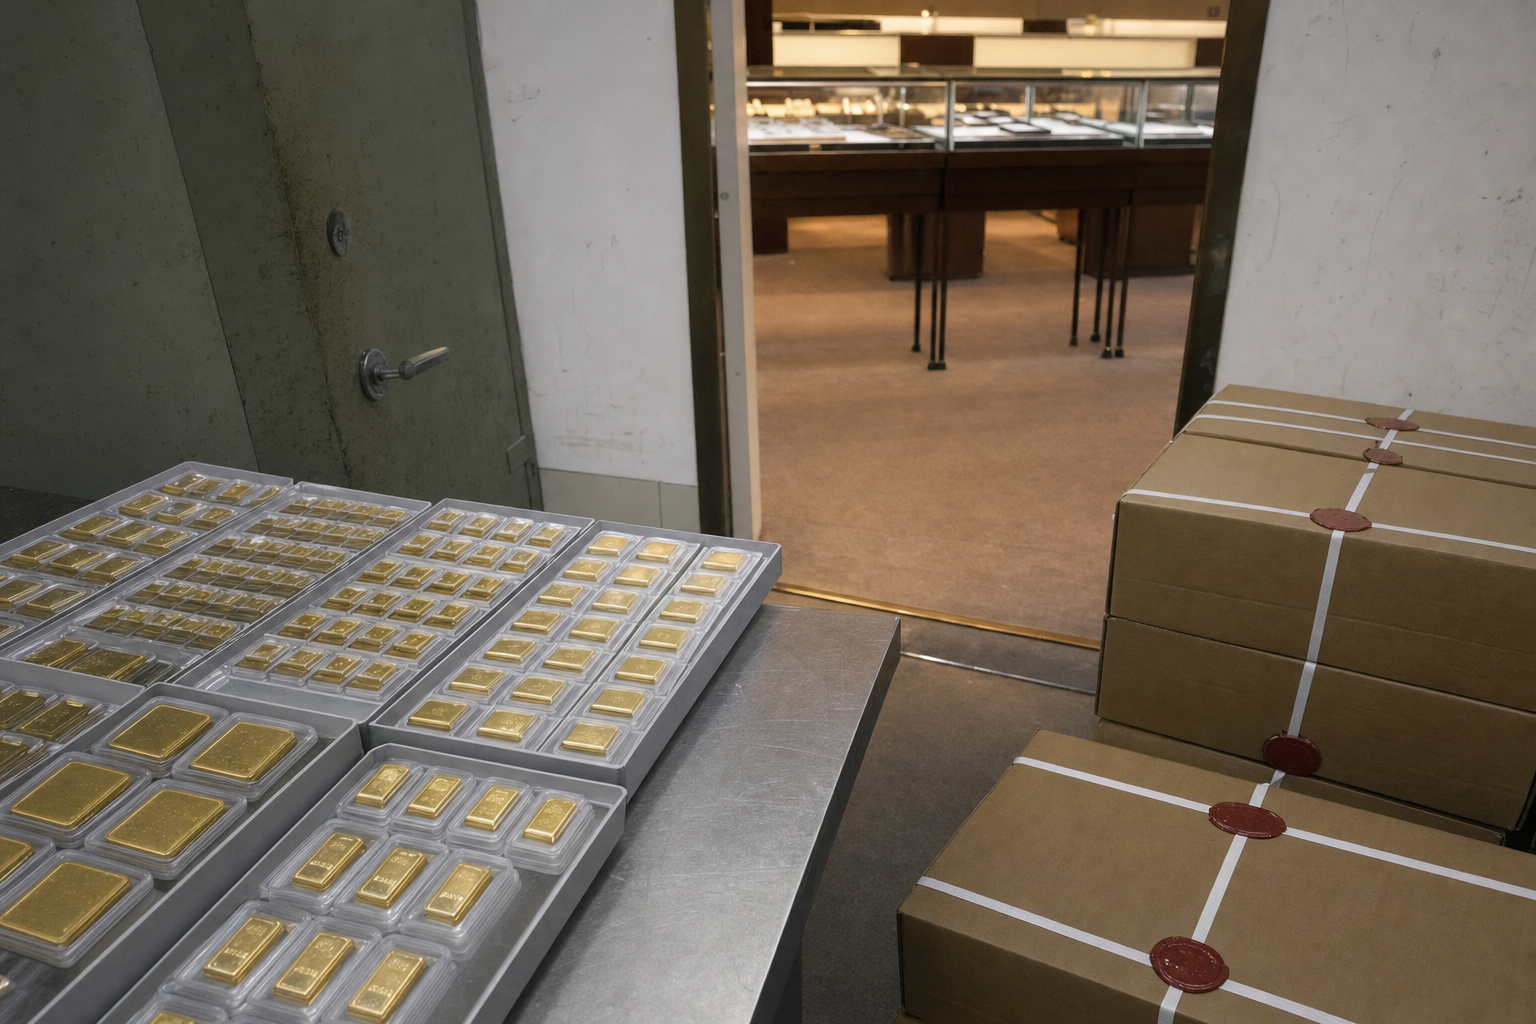
Alongside new buying, some institutions repatriated or transferred existing sovereign holdings to different storage locations during the month. These movements typically involve shifting bars between domestic vaults and established international hubs, or redistributing inventory across multiple jurisdictions to balance operational, legal and risk considerations. Such rebalancing can occur independently of net purchasing and is often timed around logistics windows and custody reviews.
Repatriation and vault transfers do not alter the aggregate level of global official-sector holdings, but they can influence bar location, bar lists and the mix of custodial arrangements. For market participants, these flows are a reminder that physical gold sits within a real supply chain of mints, refineries, carriers and vault operators, with periodic movements that may affect short‑term liquidity and settlement timing without changing underlying reserve strategy.
Market Context
The leadership of China, Uzbekistan and Poland in August aligns with a broader pattern in which a subset of central banks has been consistently active on the buy side in recent years. While individual policy frameworks differ, the inclusion of bullion in reserve portfolios is widely used to diversify across asset classes and counterparties, with the added attribute that gold is a high‑liquidity, no‑credit‑risk asset held outside the issuer system.
Official‑sector activity remains a material component of overall physical demand, complementing private investment and jewelry consumption. As reserve managers adjust positions and storage footprints, the bar‑level nature of central bank holdings highlights the importance of custody, assay standards and chain‑of‑integrity in the bullion market. For holders seeking direct exposure to metal, allocated, vaulted ownership mirrors the title and custody structure used for sovereign bars.